Life Insurance Education & Family Protection
Protect What Matters. Prepare for Tomorrow.
Clear, practical life insurance education—and a personal conversation to help you understand coverage options that may fit your family's needs.
Licensed Life Insurance Agent & Financial Educator
Meet Rafiq
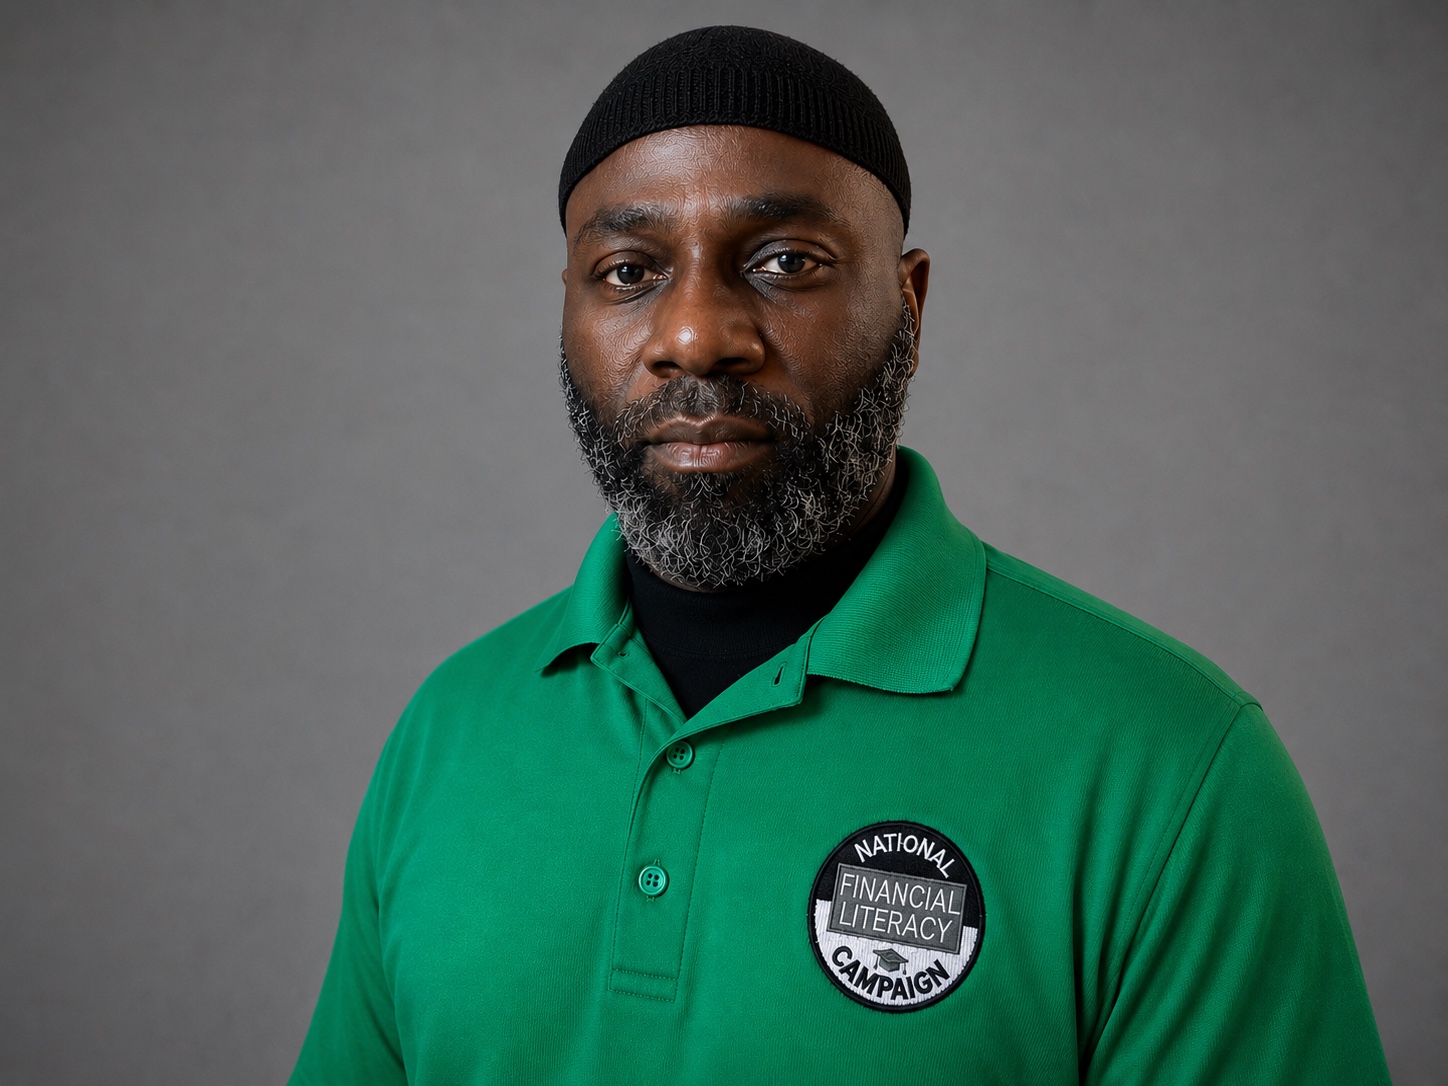
Rafiq
Licensed Life Insurance Agent & Financial Educator
New Orleans Financial Education Center
My approach is education first. I help individuals and families understand common life insurance concepts, consider their protection priorities, and ask informed questions before deciding whether to explore coverage. Every family's situation is different; conversations begin with your goals and circumstances.
Understanding Life Insurance Options
Different policy types work differently. The descriptions below are general education, not a recommendation or a promise of policy performance.
Term Life Insurance
Provides life insurance coverage for a stated period, such as 10, 20 or 30 years. It is often considered when a family wants coverage during working years, while raising children, or while paying a mortgage. Coverage generally ends when the term expires unless renewed or converted under the contract.
Whole Life Insurance
A type of permanent life insurance designed to provide coverage for life when required premiums are paid and policy conditions are met. It typically has scheduled premiums and a guaranteed cash-value structure defined by the contract. Costs are generally higher than comparable term coverage.
Universal Life Insurance
Permanent life insurance with flexible premium and death-benefit features, subject to policy terms and limits. Policy charges and credited interest affect policy values. Premium flexibility does not mean a policy can be underfunded indefinitely.
A Closer Look at Indexed Universal Life (IUL)
An IUL is a form of universal life insurance. Interest crediting is linked to the performance of an external market index through a formula in the policy; the policyholder does not directly invest in the index.
How index crediting works
Depending on the contract, index crediting may be subject to a cap, participation rate, spread, floor and other limits. These terms determine how an index change is translated into interest credited to the policy.
Costs and risks to understand
Insurance charges, fees, loans, withdrawals, changing crediting terms and insufficient premiums can reduce policy value and may cause a policy to lapse. A floor on index crediting does not prevent policy charges or guarantee that cash value will not decline.
IUL policies are complex and are not appropriate for everyone. Illustrated values are not guarantees. Review the policy contract, guaranteed and non-guaranteed values, fees, surrender charges, loan provisions and lapse assumptions with a properly licensed professional before making a decision.
Protect the People Who Depend on You
Consider how loved ones might manage everyday expenses, housing costs, childcare, education or other obligations if your income were no longer available.
Plan for Existing Obligations
Think about debts, a mortgage, final expenses and other financial responsibilities you may want life insurance proceeds to help address.
Review Your Current Coverage
Life changes. Marriage, children, a new home, a career change or retirement may be reasons to review whether existing coverage still aligns with your goals.
A thoughtful, needs-based process
1. Understand your goals and concerns
2. Review relevant coverage considerations
3. Discuss available options and limitations
4. Decide whether you want to take a next step
Submitting an inquiry does not create an insurance application or guarantee coverage. Any recommendation is subject to a complete review, licensing, carrier appointment, underwriting and policy terms.
Request a Life Insurance Conversation
If you would like to discuss life insurance education or explore whether coverage may fit your needs, share your basic contact information. Please do not include Social Security numbers, medical details, account numbers or other sensitive information.
Prefer to schedule directly? Book a general 30-minute conversation.